Bookkeeping automation can make a small business feel organised long before its records are actually reliable. A bank feed imports transactions. An AI model proposes categories. A dashboard produces a tidy profit figure. Yet a duplicated payment, misclassified owner withdrawal or missing refund can still travel quietly through the system.
The buying question is therefore not simply, “How much can this software automate?” It is: Can the system help you prove that every material number can be traced, corrected and explained?
Automation is not reconciliation
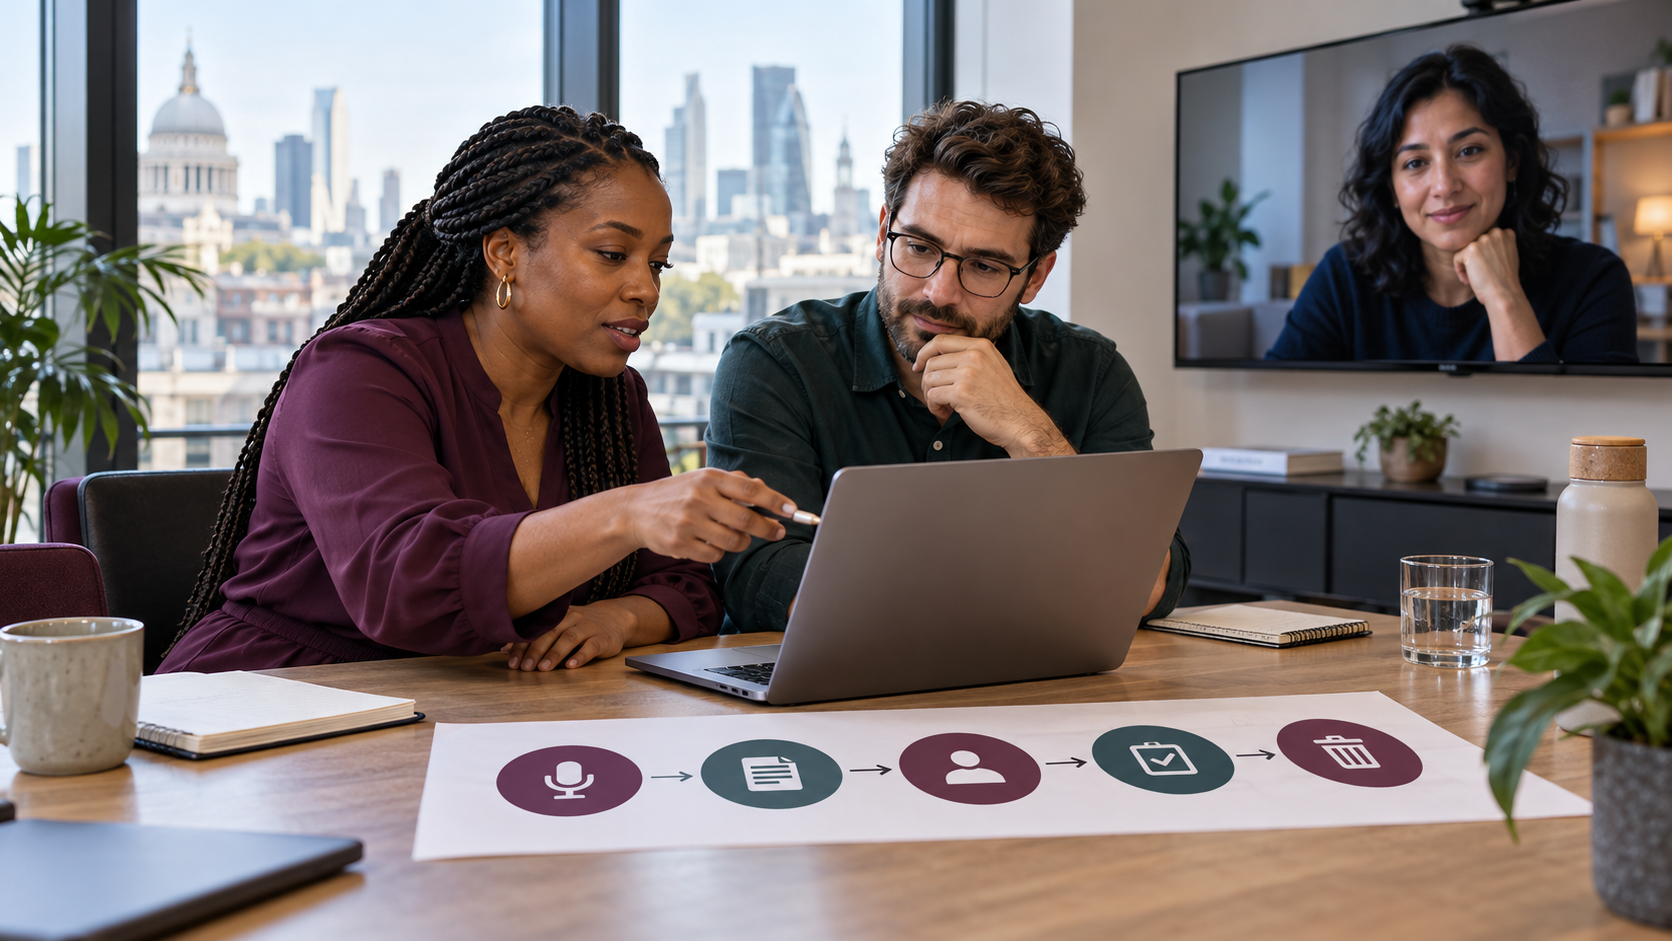
Automation moves or transforms information. Reconciliation tests whether two independent records agree. Those are different jobs.
- A bank feed may import a card payment automatically, but reconciliation checks that the imported amount matches the bank statement.
- Receipt capture may extract a supplier total, but review checks whether VAT, date, supplier and business purpose were read correctly.
- An AI categoriser may suggest “software expense”, but a human still needs to decide whether the transaction is allowable, personal, capital or mixed-use.
- A sales integration may post an order, but reconciliation checks the order against refunds, platform fees, tax and the cash actually paid out.
A useful product reduces clerical work while keeping the evidence visible. A weak product creates speed by hiding uncertainty.
Start with the records you must be able to defend
For UK buyers, software selection should begin with the records and submissions the business actually needs—not with an impressive feature list. HM Revenue & Customs says compatible Making Tax Digital for Income Tax software must support digital records, quarterly updates and the tax return. Its software finder also asks about income sources, existing records and accounting periods because compatibility is contextual rather than universal.
HMRC’s guidance, updated on 13 July 2026, says relevant software should allow users to create, store and correct records. That word correct matters. A system that can import a transaction but cannot preserve an understandable correction history leaves the buyer with a compliance and control problem.
Run a five-part reconciliation test
| Test | What to do | Evidence to retain |
|---|---|---|
| Bank-to-ledger | Import a statement containing a fee, transfer, refund and duplicate-looking payment. | Opening balance, closing balance, matched items and unresolved difference. |
| Order-to-payout | Trace one sale through tax, discount, platform fee, refund and net payout. | Order ID, payout ID, fee breakdown and refund reference. |
| Receipt-to-entry | Upload a clear receipt and a difficult one with mixed personal and business use. | Original document, extracted fields, reviewer decision and adjustment. |
| Correction history | Change a category and amount, then reverse the correction. | Old value, new value, time, user and reason. |
| Export-and-rebuild | Export a complete period and ask an accountant to reconstruct key totals. | Machine-readable files, attachments, account codes and audit log. |
Do not accept a staged demonstration using perfect sample data. Use a duplicate, a partial refund, a late supplier credit, a transaction in another currency and a payment that appears in the bank several days after the sale. These are ordinary business conditions, not edge cases.
Inspect the audit trail before the dashboard
A good audit trail should answer five questions without relying on memory:
- What changed?
- What was the previous value?
- Who or what made the change?
- When did it happen?
- Why was it approved?
Ask whether automated suggestions are visually distinguishable from approved entries. Check whether deleted items remain recoverable or at least recorded. Confirm that administrator actions are logged as carefully as ordinary-user actions. If the vendor says its AI “learns” from corrections, ask what data is retained, where it is processed and whether one client’s records can influence another client’s system.
Human review needs an operating design
“Human in the loop” is too vague to be a control. Define which events stop automation and who is authorised to release them.
- Transactions above a chosen value
- New suppliers or bank accounts
- Large category changes near a reporting deadline
- Mixed personal and business expenditure
- Unusual refunds, chargebacks or negative payouts
- Entries with low extraction or classification confidence
The reviewer also needs enough context to make a decision. A queue that displays only a proposed category—without the original receipt, bank description and related transaction—is an approval theatre, not meaningful review.
Check data responsibilities and supplier access
Bookkeeping systems can contain customer names, employee payments, supplier details and bank information. The Information Commissioner’s Office says a written contract is required when a controller uses a processor, and its guidance lists terms covering instructions, confidentiality, security, sub-processors, assistance, deletion or return of data, and audits.
Before buying, request the data-processing terms and a current list of sub-processors. Check where support staff can access records, how privileged access is logged, what happens to backups after cancellation and how the supplier will help with access, deletion or security incidents. A security badge is not a substitute for reading the actual scope and contract.
Calculate the full operating cost
The subscription price is only one line. Include implementation, migration, bank-feed charges, additional users, receipt-capture limits, payroll or tax modules, accountant access, training, review time, exception handling and exit work.
Illustrative calculation—not a customer result: suppose software costs £35 a month, human review takes two hours at an internal cost of £25 an hour, and exception clean-up averages 30 minutes. The operating cost is £97.50 a month before migration, accountant review or add-ons. If the previous process cost £100 in staff time, the saving is £2.50—not the £65 suggested by comparing labour with the subscription alone.
The same tool may still be worthwhile because it shortens month-end close, improves evidence or reduces stress. The point is to buy it for the value it actually creates.
Test retention and exit before importing everything
HMRC says self-employed people generally need to keep relevant records for at least five years after the 31 January submission deadline for the tax year. Retention obligations do not disappear because a subscription ends.
Run an exit test during the trial. Export transactions, attachments, account mappings, reconciliation reports and the audit log. Confirm whether the files are complete, readable without the vendor’s software and suitable for an accountant or replacement system. Ask how long exports remain available after cancellation and what deletion certificate or confirmation is provided.
Who this type of software suits—and who should wait
Bookkeeping automation can suit a business with recurring transaction volume, a stable chart of accounts, clear review ownership and enough clean source data to test the system. It can also help a founder whose accountant wants better documentation and a more consistent month-end process.
It may be a poor purchase for a very low-volume business that can maintain an accurate spreadsheet, a founder who will not review exceptions, or a company whose sales, refunds and payouts cannot yet be matched reliably. Automation applied to unresolved records can scale confusion.
Compare realistic alternatives
- Use existing software better: tighten account rules, monthly reconciliation and document naming before adding another product.
- Use a spreadsheet plus bridging software: HMRC recognises that some compatible tools connect to existing records rather than replacing them.
- Outsource defined work: a bookkeeper may be better value when transaction volume is modest but judgement is complex.
- Do nothing for one quarter: document the present error rate, hours and close time first. Without a baseline, automation savings cannot be measured.
A practical buying scorecard
- List every bank, sales, payroll and tax source that must connect.
- Test duplicates, refunds, fees, foreign currency and mixed-use expenses.
- Require an export of transactions, evidence and change history.
- Define the human-review thresholds and escalation owner.
- Confirm HMRC compatibility for the specific income sources and submissions you need.
- Read processor terms, sub-processor details and deletion commitments.
- Calculate monthly operating cost, not just the licence.
- Keep the old process available until two complete periods reconcile successfully.
The decision
Buy bookkeeping automation when it makes evidence easier to trace, exceptions easier to review and records easier to export. Avoid it when the main promise is a beautiful dashboard produced from transactions nobody has reconciled.
The strongest system is not the one that removes people from bookkeeping. It is the one that removes repetitive work while preserving accountable human judgement.
Optional marketplace discovery: If you are comparing software or digital-business assets, you can explore the general MOC Marketplace catalogue. MOC Marketplace is part of the MaryChuks.com business ecosystem. This is a general discovery link, not a recommendation of a specific bookkeeping product or a guarantee that a listing’s claims have been independently verified.
Sources and further reading
- HMRC: Choose the right software for Making Tax Digital for Income Tax
- HMRC: Find software that works with Making Tax Digital for Income Tax
- HMRC: Create digital records for Making Tax Digital for Income Tax
- ICO: What needs to be included in a controller–processor contract?
- HMRC: How long self-employed people must keep records
- MaryChuks: Calculate contribution margin per order
This article provides general editorial decision support, not accounting, tax, legal or data-protection advice. Requirements depend on the business, jurisdiction and reporting obligations.
Discover more from Marychuks.com AI, Psychology, Business & CreativeVerse
Subscribe to get the latest posts sent to your email.