Slug: property-flood-risk-home-viewing-audit
Tags: Property, Safety Property buying tips, flood
Meta description: A dry viewing cannot prove a home is flood-safe. Use this UK property audit to check maps, history, drainage, insurance and resilience before committing.
A bright viewing on a dry afternoon can conceal one of a property’s most consequential risks. Fresh paint may cover a water mark. New paving may direct rain towards the door. A river may be distant while intense rainfall overwhelms local drains.
Flood risk should not automatically end a purchase. It should change the questions, evidence and price of uncertainty. The aim is to understand the source of risk, the property’s history, the likely cost of insurance and recovery, and whether practical resilience measures already exist.
1. Begin with the official map—but read its limits
For a home in England, start with the Government’s long-term flood-risk service. It covers risk from rivers and the sea, surface water, reservoirs and groundwater where data is available, and it can show how climate change may affect an area.
The service is an area-level screening tool, not a guarantee about one building. Its own guidance says it does not predict whether an individual property will flood and does not cover every source, such as blocked drains or burst pipes. A low-risk map result therefore means “continue checking”, not “risk eliminated”.
- River and sea: water escaping a watercourse or coastal flooding.
- Surface water: intense rain flowing or pooling before drains and ground can absorb it.
- Groundwater: the water table rising into basements, floors or surrounding land.
- Reservoir: the modelled consequence of a rare failure; likelihood and consequence are different questions.
2. Ask for history, not reassurance
“It has never flooded while we have lived here” is not a complete history. Ask in writing whether the building, garden, access road, cellar, garage or outbuildings have experienced flooding, water ingress, sewer backup or repeated ponding. Ask when, how deep, from which source, what repairs were made and whether insurers or public bodies were involved.
In England, you can also request flood-history information for the area around an address from the Environment Agency. The Agency warns that it does not hold records for every location. “No record found” is therefore evidence about the database, not proof that no event occurred.
3. Read the street before the rooms
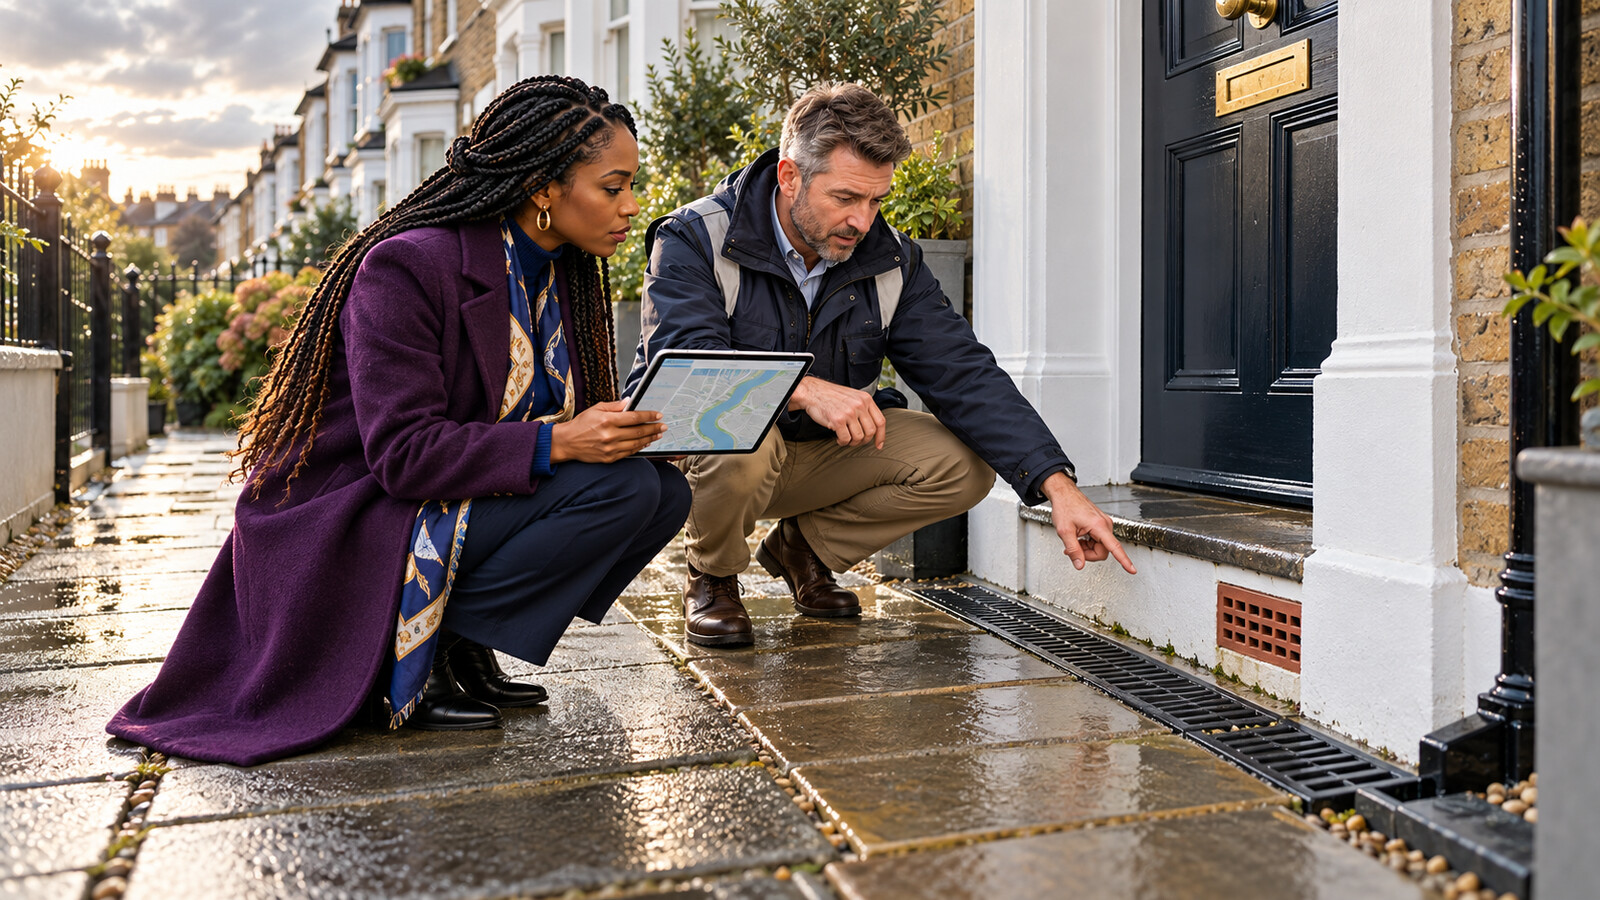
Arrive early and walk beyond the front door. Look for the direction of the slope, the height of the threshold, low points in paving, nearby watercourses, culverts, retaining walls and drains. Ask where water would travel during a cloudburst. Visit after rain if practical, without entering unsafe water or private land.
At the building, note air bricks close to ground level, basement openings, steps descending towards doors, patched render, tide marks, flaking paint, persistent musty odour and recently replaced lower plaster or skirting. None of these is proof of flooding on its own. They are prompts for a surveyor and documentary questions.
4. Distinguish protection from resilience
A flood wall, embankment or drainage scheme can reduce risk without abolishing it. Defences can be overtopped, fail or leave residual risk from another source. Property-level measures also serve different purposes:
- Resistance aims to stop or delay water entering, using measures such as suitable barriers, non-return valves or protected openings.
- Recoverability accepts that some water may enter and reduces damage through appropriate floors, raised electrics, resilient materials and accessible services.
The Environment Agency describes property flood resilience as modifications that can lower damage and speed recovery, while stating that risk cannot be removed entirely. Its property adaptation guidance provides a starting point. Any measure should be appropriate to the building and installed with competent advice; a badly chosen barrier can move water elsewhere or trap it.
5. Treat insurance as a pre-offer test
Do not assume that because the current owner is insured, you will receive equivalent cover at an affordable price. Before becoming legally committed, seek realistic buildings-insurance quotations using accurate information about the property and known history. Compare flood excesses, exclusions, alternative accommodation, repair conditions and any requirements to maintain resilience equipment.
Flood Re may help eligible UK households access flood cover through participating insurers, but eligibility is not universal and buyers do not purchase directly from Flood Re. Avoid treating the scheme as a blanket guarantee. The Government’s flood-insurance guidance also notes that owners who have completed resilience work can prepare a Flood Risk Report for insurers or buyers.
6. Commission the right expertise
A standard survey may flag visible damp or location concerns, but complex risk can justify more specific investigation. Tell the surveyor what the maps, seller and street inspection revealed. Ask whether the scope includes drainage, basements, previous repairs and property-level resilience. For higher or ambiguous risk, consider a specialist flood assessment and drainage survey.
Keep the roles clear. A map models an area. A conveyancer investigates legal and search information. A surveyor evaluates the building within the agreed scope. An insurer prices cover under its own criteria. One professional’s answer does not automatically substitute for the others.
7. Audit the recovery pathway
Risk is not only the chance of water arriving. It is also the consequence and time to recover. Ask:
- Where are the consumer unit, boiler, sockets and valuable equipment?
- Are bedrooms or an accessible exit available above the likely flood level?
- Could occupants with children, disabilities, pets or caring responsibilities leave safely?
- Would one flooded access road isolate the property even if the interior stayed dry?
- How long might drying, decontamination and repairs make the home uninhabitable?
- Where would vehicles, medicines, documents and irreplaceable items go after a warning?
This converts an abstract probability into a household decision. Two buyers can reasonably value the same risk differently because their mobility, finances, work and support networks differ.
8. Separate evidence, interpretation and speculation
Evidence includes official map outputs, documented history, survey findings, drainage information, quotations and photographs. Interpretation is a professional or buyer’s judgement about what those facts mean for this building. Speculation includes claims such as “the council will fix it soon” or “climate change will not affect this road” without a funded plan or supporting analysis.
The Environment Agency reported in June 2026 that about 6.3 million properties in England are in areas at risk from rivers, the sea, surface water or a combination, with surface water accounting for the largest group. That national estimate establishes scale, not the fate of a particular home. Use it to justify diligence, not panic. See the Agency’s published explanation.
A practical pre-offer record
- Save dated screenshots or reports for every flood source checked.
- Request the area’s recorded flood history.
- Send written questions to the seller through the proper channel.
- Photograph drainage, thresholds and suspicious repairs with permission.
- Share concerns with the surveyor and conveyancer before agreeing their scope.
- Obtain credible insurance terms, including the flood excess.
- Estimate resilience, maintenance and recovery costs—not just the purchase price.
A dry viewing is only one observation
Property decisions often reward confidence, yet flood risk requires disciplined uncertainty. Maps can miss property detail. Sellers may have limited knowledge. Defences reduce rather than erase risk. Climate and development can alter how water moves.
The responsible conclusion may be to proceed, renegotiate, require further investigation or walk away. What matters is that the decision rests on documented evidence and a realistic recovery plan—not the weather on viewing day.
This article provides general information for England and is not legal, surveying, insurance or financial advice. Flood-information services differ across Scotland, Wales and Northern Ireland.
Featured image: original conceptual AI-generated illustration created for this article. It does not depict a real property, buyer, surveyor or flood-risk assessment.
Discover more from Marychuks.com AI, Psychology, Business & CreativeVerse
Subscribe to get the latest posts sent to your email.


